How to Start a Consumer Lending or BNPL Business
Published on: 2026-04-05 23:46:54
Starting a consumer lending or BNPL business is not about launching a loan product and hoping demand appears. It is about building a licensing, funding, decisioning, servicing, and collections operation that can scale and keep control of risk. This guide breaks down the core business models, operating flow, technology stack, and decision logic you need to run it.
The consumer lending operating model
There is no single path into consumer lending. The right structure depends on what you lend, who funds it, how you acquire borrowers, and how you manage risk. A BNPL platform, a short-term lender, and a revolving credit business all use different economics, different compliance requirements, and different decision flows.
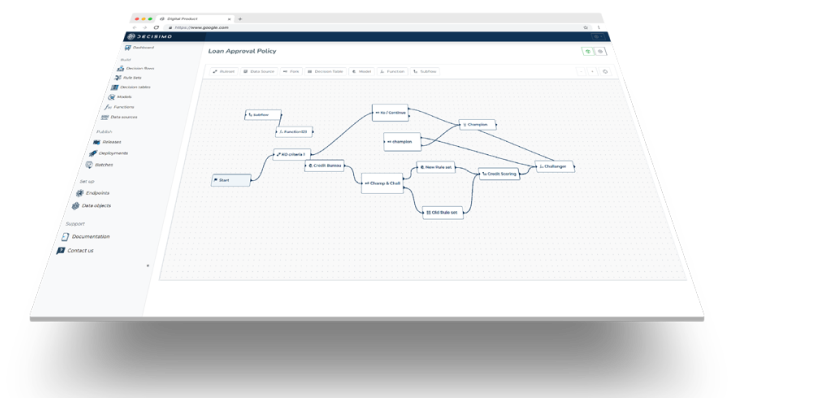
What they share is a simple requirement: the same policy should produce the same loan decision, and each decision should leave a trace that explains the outcome. If you cannot find the decision trace showing why a borrower was approved, declined, priced, or routed to collections, the business will be hard to control.
That is why the first question is not “How do we grow fast?” It is “How do we build a lending operation that can make deterministic decisions as lending volumes grow?”
Understand the main consumer lending models
Consumer lenders offer several kinds of loans. For each loan type, borrowers follow a different repayment schedule, the lender earns a different margin, and the lender faces different risks. Before you raise funding or build a platform, you need to choose the loan model that matches your market.
Consumer durable installment lending and BNPL
Consumer durable installment loans pay for furniture, appliances, or electronics that people use for 3 years or more. BNPL is a narrower version of these loans: it usually divides the purchase into 3 or 4 equal payments over a short term, often weekly or bi-weekly.
BNPL works well when merchants offer it at the point of sale: it converts there. The merchant gets larger baskets and more completed purchases. The lender handles many small transactions. The challenge is keeping the channel under control. You need quick decisions, strong fraud checks, and a merchant network that stays clean.
Short-term installment loans
Short-term installment loans are loans for smaller amounts with terms under 1 year. In many markets, payday loans and salary loans fall into this category. Borrowers often repay the loan in a single lump sum at the end of the term, which puts more pressure on collections teams and affordability checks.
These products can produce strong returns, but they depend on the rules lenders must follow, the dates borrowers pay, and the money borrowers have available. Approval rules have to be strict. If the product accepts borrowers who cannot repay on the due date, losses rise fast.
Longer-term cash loans
Longer-term cash loans usually run for more than 1 year and are repaid in monthly installments. Those monthly payments spread repayment risk across the loan term, but the lender’s money remains committed for longer. These loans need a more thorough review of each borrower, enough money available to fund them, and regular reviews of the loans in the portfolio.
For this model, an underwriter often compares the borrower’s debt with their income, reviews the borrower’s bureau record, verifies the borrower’s income, and sets the price according to risk.
Credit lines and revolving products
A credit line gives the borrower a borrowing limit they can use in separate draws over time. Interest applies only to the amount currently drawn. This model is common in cards and revolving credit products. It is more complex than a closed-end loan because the amount borrowed can change, repayments can change, and the lender must check the account and limit continuously.
If you run a revolving product, the decision engine does not stop at approval. It keeps evaluating account behavior, exposure, delinquency, and limit changes.
Get the regulatory model right first
Consumer lending is regulated in every jurisdiction. The exact rules vary, but the pattern is the same. A lender must treat each borrower fairly, give borrowers clear terms, check whether each borrower can repay, and avoid lending an amount that the borrower cannot reasonably handle.
Many markets require a lending license. Some set a maximum interest rate. Others require a particular product structure, such as a Sharia-compliant one. If you launch before checking the required license, interest rate cap, and product structure, you can end up with a product that cannot operate.
This is not a legal detail to handle later. It shapes the product from day one.
- Disclosures: borrowers must understand the cost, term, and repayment schedule.
- Affordability: the lender must assess whether the borrower can repay.
- Rate limits: some jurisdictions cap interest or fees.
- Licensing: lending activity may require formal authorization.
- Local structure: product design may need to fit religious or consumer protection rules.
Secure funding before you scale origination
You cannot originate loans without money available to fund them. That means the business needs money on its balance sheet or money from external funding partners. In practice, lenders may be banks, private equity firms, family offices, or other capital providers willing to put money into a group of loans.
There are two common arrangements. In one, the lender keeps the loans in its own accounts. In the other, the lender provides the money for a portfolio, and the platform originates the loans for that lender. In the second arrangement, the people who make loan decisions, manage repayments, and prepare reports often need to coordinate more closely.
Some businesses also explore peer-to-peer lending. In that model, retail investors fund loans directly. It can work, but the operating complexity is high. You need enough borrowers on one side and enough investors on the other, and if either side dries up, the model breaks.
A real operational risk arises when borrowers apply and no capital is available, or when capital is available and no applications meet the eligibility rules. Your platform needs decision logic and portfolio rules that account for both.
Build the acquisition model around your product
Once you have chosen the loan product and decided how the loans will be funded, you need channels that bring borrowers to you. Consumer lending businesses usually find borrowers through one of four channels: loan comparison sites, loan origination platforms, merchant networks, or a sales force.
Loan comparison sites
Loan comparison sites show multiple loan products side by side so consumers can compare their terms. Lenders usually pay for a place in the listings, for each lead they receive, or for successful conversions. These sites can send lenders a high volume of leads, but they often send the same lead to multiple lenders.
That makes the pre-approval rule set important. If your eligibility rules accept too many poor-fit applicants, you waste time and capital on them. If they reject too many applicants, you lose volume.
Loan origination platforms
Loan origination platforms put borrowers in contact with lenders and often present the lender’s product under another company’s name. They may show borrowers repayment information, help handle applications, and send them to the funding partner.
Advanced platforms sometimes connect to a lender’s decision logic endpoint for pre-approval. That endpoint usually runs basic checks, compares the application with block lists, and applies KO criteria before the application moves forward. This is where deterministic decisions matter. You want to see each rule, test it, and follow the decision it produces.
For a deeper look at how decision rules fit into the product, see Working with Basic Rules and Implementing scorecards in rule engines.
Merchant networks
Merchant networks are common in BNPL and consumer durable lending. At checkout, merchants show customers the financing option, which leads more customers to complete purchases and increases the amount spent in each purchase. The lender reaches those customers through the merchants. The merchant makes more sales.
This model works when many merchants promote the product regularly and follow the agreed rules. It also creates fraud exposure, because merchants may act differently depending on the channel, location, or incentive.
Sales force
Some lenders build their own sales teams. Salespeople may work online, offline, at events, through referrals, or through direct outreach. They can generate a high number of leads and stay in close contact with merchants, but paying for the team is costly.
It also introduces control risk. Sales teams can misrepresent product terms, push ineligible applicants, or create fraud exposure. That is why monitoring quality matters. Mystery shopping, call reviews, and application traceability are not optional if the channel is material. For more on channel testing, see Mystery Shopping in Lending: How to Test Third-Party Sales Channels.
Design the origination flow before launch
Loan origination receives applications, checks each application against eligibility rules, and sends applications that pass those checks to lenders for a decision. The application path looks simple on paper. In production, the origination system must check applications for fraud, add data to them, apply credit policy, route them, and handle applications that do not follow the normal path.
- The borrower applies online or in person.
- The application is screened for eligibility.
- The system checks policy, block lists, and KO criteria.
- Eligible applications move to the lender or funding partner.
- The lender makes the credit decision.
- The borrower receives an offer.
- The documents are signed.
- The loan is funded and disbursed.
Every step should be logged. Every rule version should be tracked. Every decision trace should be available for audit and dispute handling.
If you want to see how to structure this flow, read Step-by-Step Guide to Automating the Loan Approval Process and Tracing Models and Decisions.
Service the loan after funding
Origination is only the beginning. Once the loan is funded, the business must service it. That includes collecting payments, answering borrower questions, updating accounts, and managing late payments.
Servicing is where poor operational design shows up. If payments are posted late, if customer queries are not handled, or if delinquency is not flagged early, the portfolio weakens. A good servicing stack connects payment processing, customer support, account management, and collections.
What happens after a missed payment matters too. A collections team starts work when a borrower misses a payment. From there, the business may send notices, make calls, negotiate repayment, or hand the account to a third-party agency. In some cases, delinquent loans are sold to debt buyers.
For a structured view of this stage, see A Practical Guide to Collections Stages in Lending and Promise to Pay in Consumer Lending: How to Track, Test, and Improve Collections.
Manage risk at the portfolio level
Consumer lending businesses face credit risk, operational risk, compliance risk, reputation risk, and legal risk. These risks do not stay in separate boxes. They interact.
Credit risk grows when underwriting is weak and operational risk grows when processes are manual. Compliance risk grows when policy is undocumented. Reputation risk grows when borrowers do not understand the product. Legal risk grows when the business operates outside local rules.
Portfolio management is the discipline that keeps these risks visible, and it means reviewing performance, identifying loans that show stress, and taking action before losses widen. It also means understanding cohort behavior, repayment speed, and customer lifetime value.
A practical portfolio team watches the full lifecycle. It does not just look at approval rates. It tracks delinquencies, cure rates, roll rates, and repeat borrowing behavior. If you need a broader framework, see Portfolio management in lending: what matters most and Metrics to Monitor in Lending and Credit Underwriting.
Use decision logic to control approvals, pricing, and routing
A consumer lending platform needs more than a rules engine. It needs explicit decision rules for evaluating eligibility, detecting fraud, applying policy, pricing risk, and routing applications according to the lender’s appetite.
In mature setups, the lender or platform exposes a decision endpoint that checks an application before approval. It can check the applicant’s affordability and identity, compare the application with block lists, and choose a route. If the application passes, the lender can apply a deeper credit policy. If it fails, the system should return the reason clearly.
This matters because consumer lending changes fast. A lender’s funding criteria change. The risk levels used in decisions change. Regulations change. Merchant quality changes. A process with rules fixed in code becomes fragile. A decision engine with configurable rules keeps the business moving and does not turn every policy update into a development project.
For more on policy design, see decision strategy in scaled lending.
Plan for fraud from the start
A loan application brings together a borrower’s identity, access to money, and a fast decision, and this makes lending a fraud target. A sales team, a merchant checkout, and an online application each give fraud a route into the lending operation. Fraud is not a side issue. It belongs in the operating model.
Common checks include confirming the applicant’s identity, reviewing information about the device used, confirming the applicant’s address, reviewing the email address, and reviewing the merchant’s behavior. The checks you use depend on the risk in the channel and the value of the product. A BNPL application with an instant decision uses different checks from a longer-term cash loan reviewed manually by an underwriter.
Fraud controls should be linked to decision logic, not bolted on later. When a signal changes, the platform should be able to update the rule, test the effect, and trace the decision. For related reading, see Building Anti-Fraud Competency Without Lock-In and Antifraud investigation in lending: how to detect, trace, and validate risk.
Choose an architecture that matches the business
The usual consumer lending stack includes an app for customers, an app for merchants or sales teams, a core loan origination system, a payment-processing system, a loan approval system, a collections system, CRM software, call center software, a data warehouse, and an analytics system.
That stack only works if the systems pass decisions and data between them cleanly. The loan approval system should not hide the decision behind a black box. It should show the decision traces, rule versions, and outcomes. The data warehouse should keep enough history for monitoring, audits, and model review.
At minimum, the architecture should support:
- borrower onboarding and application capture
- eligibility and fraud screening
- credit and pricing decisions
- loan servicing and repayment tracking
- collections and promise-to-pay processes
- portfolio analytics and reporting
- audit trails and compliance evidence
If your team is still mapping the system, review API endpoints explained and How to implement an automated decision strategy that keeps working under failure.
Increase lifetime value. Do not weaken risk controls.
Lifetime value matters in consumer lending because acquisition is expensive. The best customers are often those who return, repay, and qualify for better products later. That is why lenders look at cross-sell and upsell paths after the first loan.
A BNPL customer may later qualify for a credit line. A cash-loan customer may later receive a higher limit. A repeat borrower may later be placed in a lower-risk segment and offered better pricing. These changes can improve revenue, but only if the risk rules stay tight.
Growth should come from better decisions, not weaker policy.
What to do first
If you are building a consumer lending or BNPL business, start with the operating model. Define the product, the funding source, the regulatory constraints, and the acquisition channel. Then define the decision logic for approval, pricing, fraud, servicing, and collections.
Once those pieces are in place, the rest becomes manageable. Without them, growth will create noise, manual work, and avoidable risk.
Consumer lending scales when the process is deterministic, auditable, and aligned to the actual business model. That is the difference between a lending operation that grows and one that only looks busy.
